Voima Weekly #57 – Looking Beneath the Price
Marko Viinikka
Toimitusjohtaja
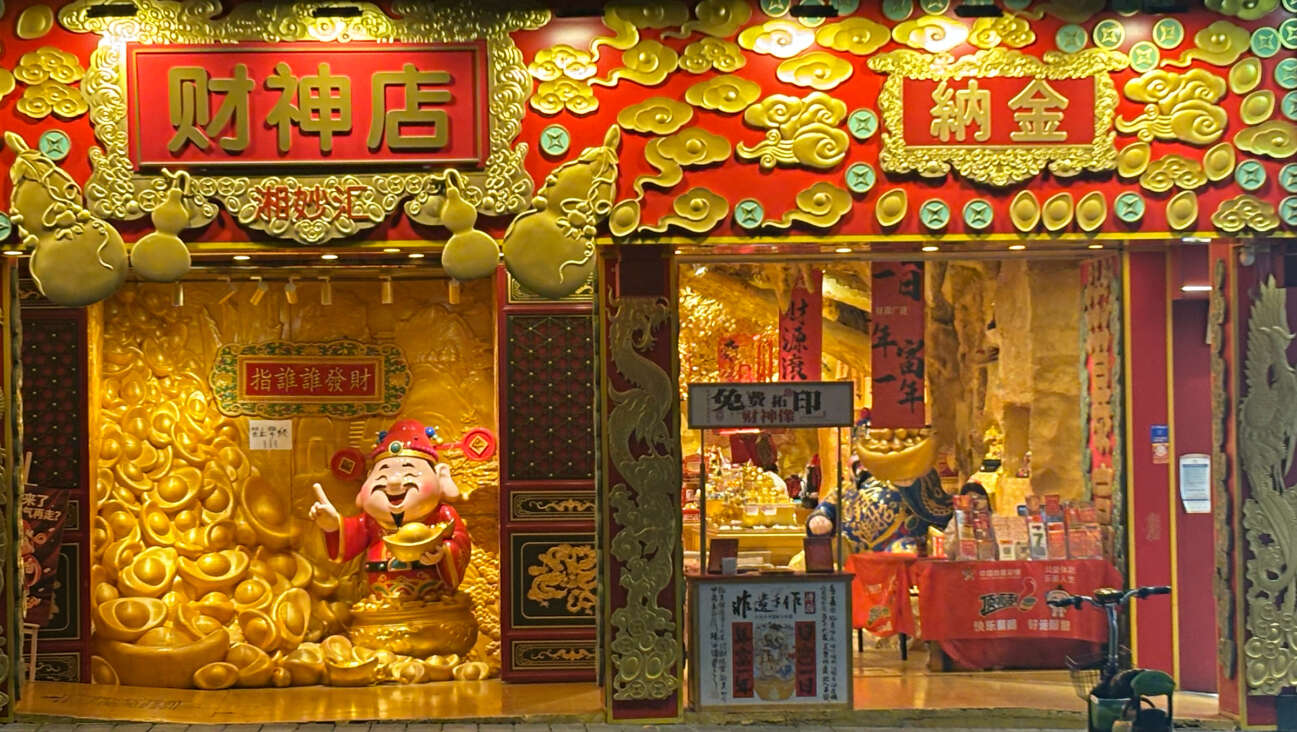
In China, gold is also a symbol of wealth and good fortune. In Changsha, I came across a themed shop dedicated to the “god of wealth.” Gold ingot-shaped decorations and inscriptions wishing people prosperity speak to gold’s place in the culture - long before daily price charts. Photo taken with my own camera.
Last week, I travelled to China on business. During the trip, I also had the opportunity to visit Shenzhen’s Shuibei precious metals market. There, the scale of the business surrounding gold becomes tangible. Individuals and families buy and sell gold, and an entire network of businesses operates around precious metals.
The area’s gold and jewellery industry is reported to exceed 200 billion yuan annually. Divided by the number of days in a year, that represents tens of millions of euros per day. The market is large, and gold is a visible part of people’s everyday lives.
During the trip, gold was priced at around 850,000 yuan per kilogram. In euros, we have been talking about roughly €120,000. In Japanese yen, the same kilogram of gold costs around 20 million, and in Turkish lira, more than six million. Yet a kilogram of gold remains the same.
The size of the number alone does not tell us whether gold is expensive. A more interesting question is how much gold the same amount of money buys at different points in time. At the beginning of the euro era in 1999, a kilogram of gold cost around €8,000. When we say that the price of gold has risen, we are also saying that the euro’s purchasing power, measured in gold, has fallen.
Gold’s high nominal price often tells us more about developments in the local currency than about gold itself, which is why nominal prices differ so greatly.
Behind this are local economic conditions, monetary policy and confidence in the currency. When the money supply persistently grows faster than economic output and the demand for money, its purchasing power comes under downward pressure. Buying the same amount of gold then requires an increasing number of currency units. A rising gold price also makes visible what is happening to money.
But why is gold a justified point of comparison? Gold has served as money somewhere in the world for more than 2,500 years. It is one of humanity’s longest-standing ways of preserving and transferring wealth.
Our current monetary system also has its roots in gold-backed money. Under the Bretton Woods system, currencies were pegged to the dollar, and the dollar was pegged to gold. The United States stopped converting dollars into gold for foreign monetary authorities in August 1971. The major currencies moved to floating exchange rates in 1973.
Central banks continue to hold gold in their reserves alongside foreign currency assets. Physical monetary gold has a special status: it is a financial asset that is not matched by anyone else’s liability. Its existence does not depend on an issuer’s ability to pay, nor can more of it be created through a monetary policy decision.
This makes gold a justified long-term benchmark for money. It does not mean that gold’s purchasing power is constant or that its price precisely tracks the cost of living. Gold supply, demand and investor expectations also change.
That is why investors should look beneath the price. If gold falls by five per cent, what has actually changed in the economy? Has money supply growth slowed? Has borrowing decreased? Have interest rates or confidence in currencies changed? Or have changes mainly occurred in the market’s short-term expectations?
My own assessment is that the pressures created by rising debt and the need to finance it could further accelerate growth in money supplies and nominal prices in the years ahead. This does not mean a steady rise in the price of gold. It means that watching the price chart alone leaves an essential part of the picture unseen.
For long-term savers, an important question is what is happening to the money in which their wealth is measured.
Wishing you a good week ahead.
–Marko Viinikka
Founder, CEO
Voima Gold Oy
Disclaimer: Voima Weeklies are the personal writings of the undersigned. They do not necessarily represent the official view of Voima Gold Oy or any other company, nor do they constitute investment advice or a recommendation to purchase securities.
You may like these
Below you will find related Voima Weekly publications where we explore economic developments, purchasing power, and the role of gold from different perspectives.2026-11-02
Voima Weekly #56 – Positioning Begins with a Clear Picture of Where We Stand
Positioning begins with an honest picture of where we stand. Gold's October 30 drop and the long-term money backdrop are two different time horizons.
2026-10-26
Voima Weekly #55 – To the Moon
The world's broad money supply stacked in $100 bills: the 2003 stack reached geostationary orbit, the 2026 stack almost halfway to the Moon. Tracking money growth helps show where new money may flow.
2026-10-05
Voima Weekly #52 – Gold as Collateral for Government Debt?
The U.S. national debt has passed $40 trillion, and gold has entered the conversation. Could gold become collateral for a new kind of government bond?
